TD Cowen kicked off coverage of SpaceX with a Buy rating and a $200 price target, implying roughly 35% upside from the company’s closing price of $148.68 on September 25. The bull case rests on AI compute leasing revenues projected to jump from $14 billion in 2026 to $133 billion by 2028. Analyst John Blackledge pinpointed SpaceX’s emerging AI compute leasing business as the primary near-term growth catalyst, stacking it alongside the continued expansion of Starlink’s subscriber base and the company’s dominant position in commercial launch services. The numbers behind the bullishness Total company revenue is expected to climb from approximately $18.7 billion in 2025 to $40.9 billion in 2026, then vault to $113.2 billion in 2027. EBITDA follows a similarly aggressive trajectory, rising from $6.6 billion in 2025 to $60.8 billion in 2027. The engine behind these projections is AI compute leasing, which TD Cowen expects to represent about 35% of total revenue in 2026 before growing to roughly 60% in 2027. In dollar terms, AI compute revenues alone are forecast at $14 billion in 2026, $66 billion in 2027, and $133 billion in 2028. Starlink’s subscriber trajectory TD Cowen’s analysis pro...
TD Cowen initiates SpaceX at Buy, sees $200 price target driven by AI compute leasing
 1 week ago
4
Related
First National Bank opens Bitcoin trading to nearly 9 millio...
20 minutes ago
0
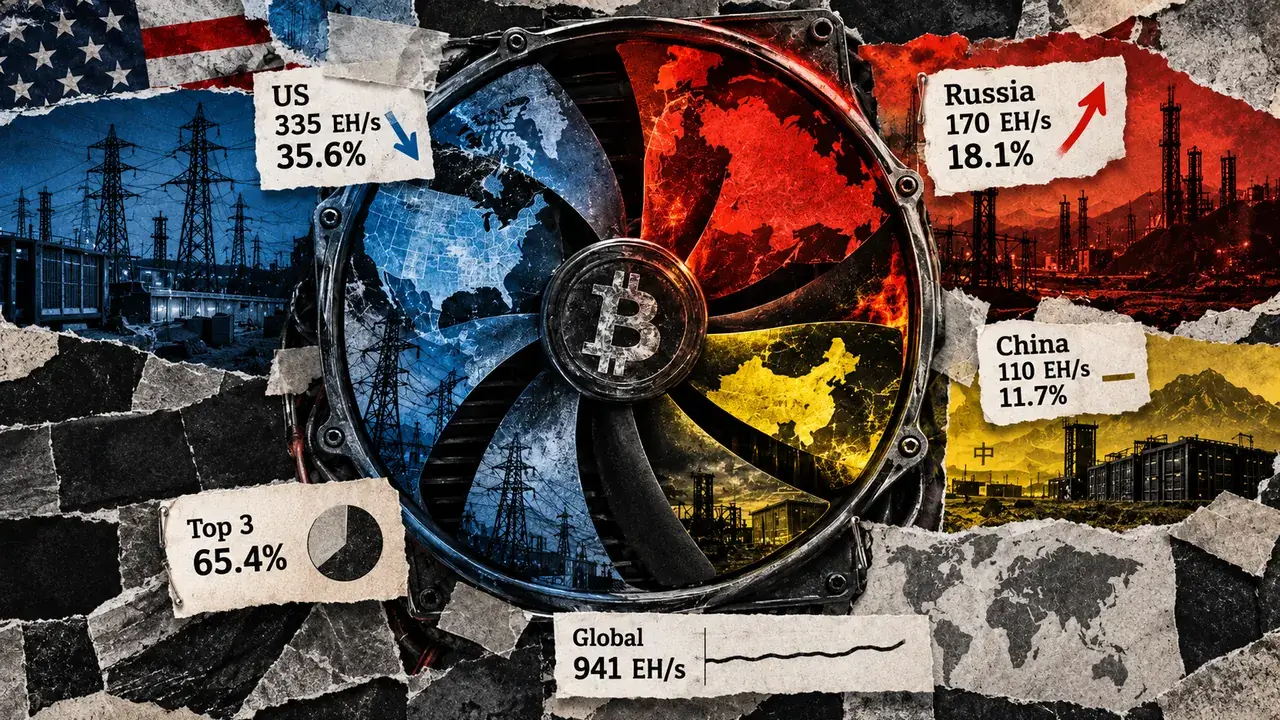
3 countries control 66% of Bitcoin mining, but 1 rival is ga...
25 minutes ago
1
Securitize, LG CNS partner on tokenized assets in South Kore...
30 minutes ago
0
Altcoins Are Rallying, But Analyst Says Alt Season Has Yet t...
33 minutes ago
0
UK names 6 banks to lead first digitally native government b...
36 minutes ago
0

Anthropic expands Cyber Verification Program with new access...
49 minutes ago
0
Winklevoss files for spot Zcash ETF as ZEC price climbs abov...
49 minutes ago
0
Saudi-backed forces launch campaign against Houthis after Re...
58 minutes ago
1
Popular

Starknet shields 45 assets with new privacy framework
4 weeks ago
100


Chainflip loses 736,442 USDT in TRON exploit
3 weeks ago
42
 English (US) ·
© Clint's Cryto News 2026. All rights are reserved
